Starter
For a single company bringing its first leases out of a spreadsheet.
$49
per month, per organization
- 5 active leases
- 1 legal entity
- Unlimited users
- 2 GB documents
Leasecount is the IFRS 16 and ASC 842 subledger for finance teams. Approved contract facts become schedules, journals and a reviewed period close, and every number traces back to the clause it came from.
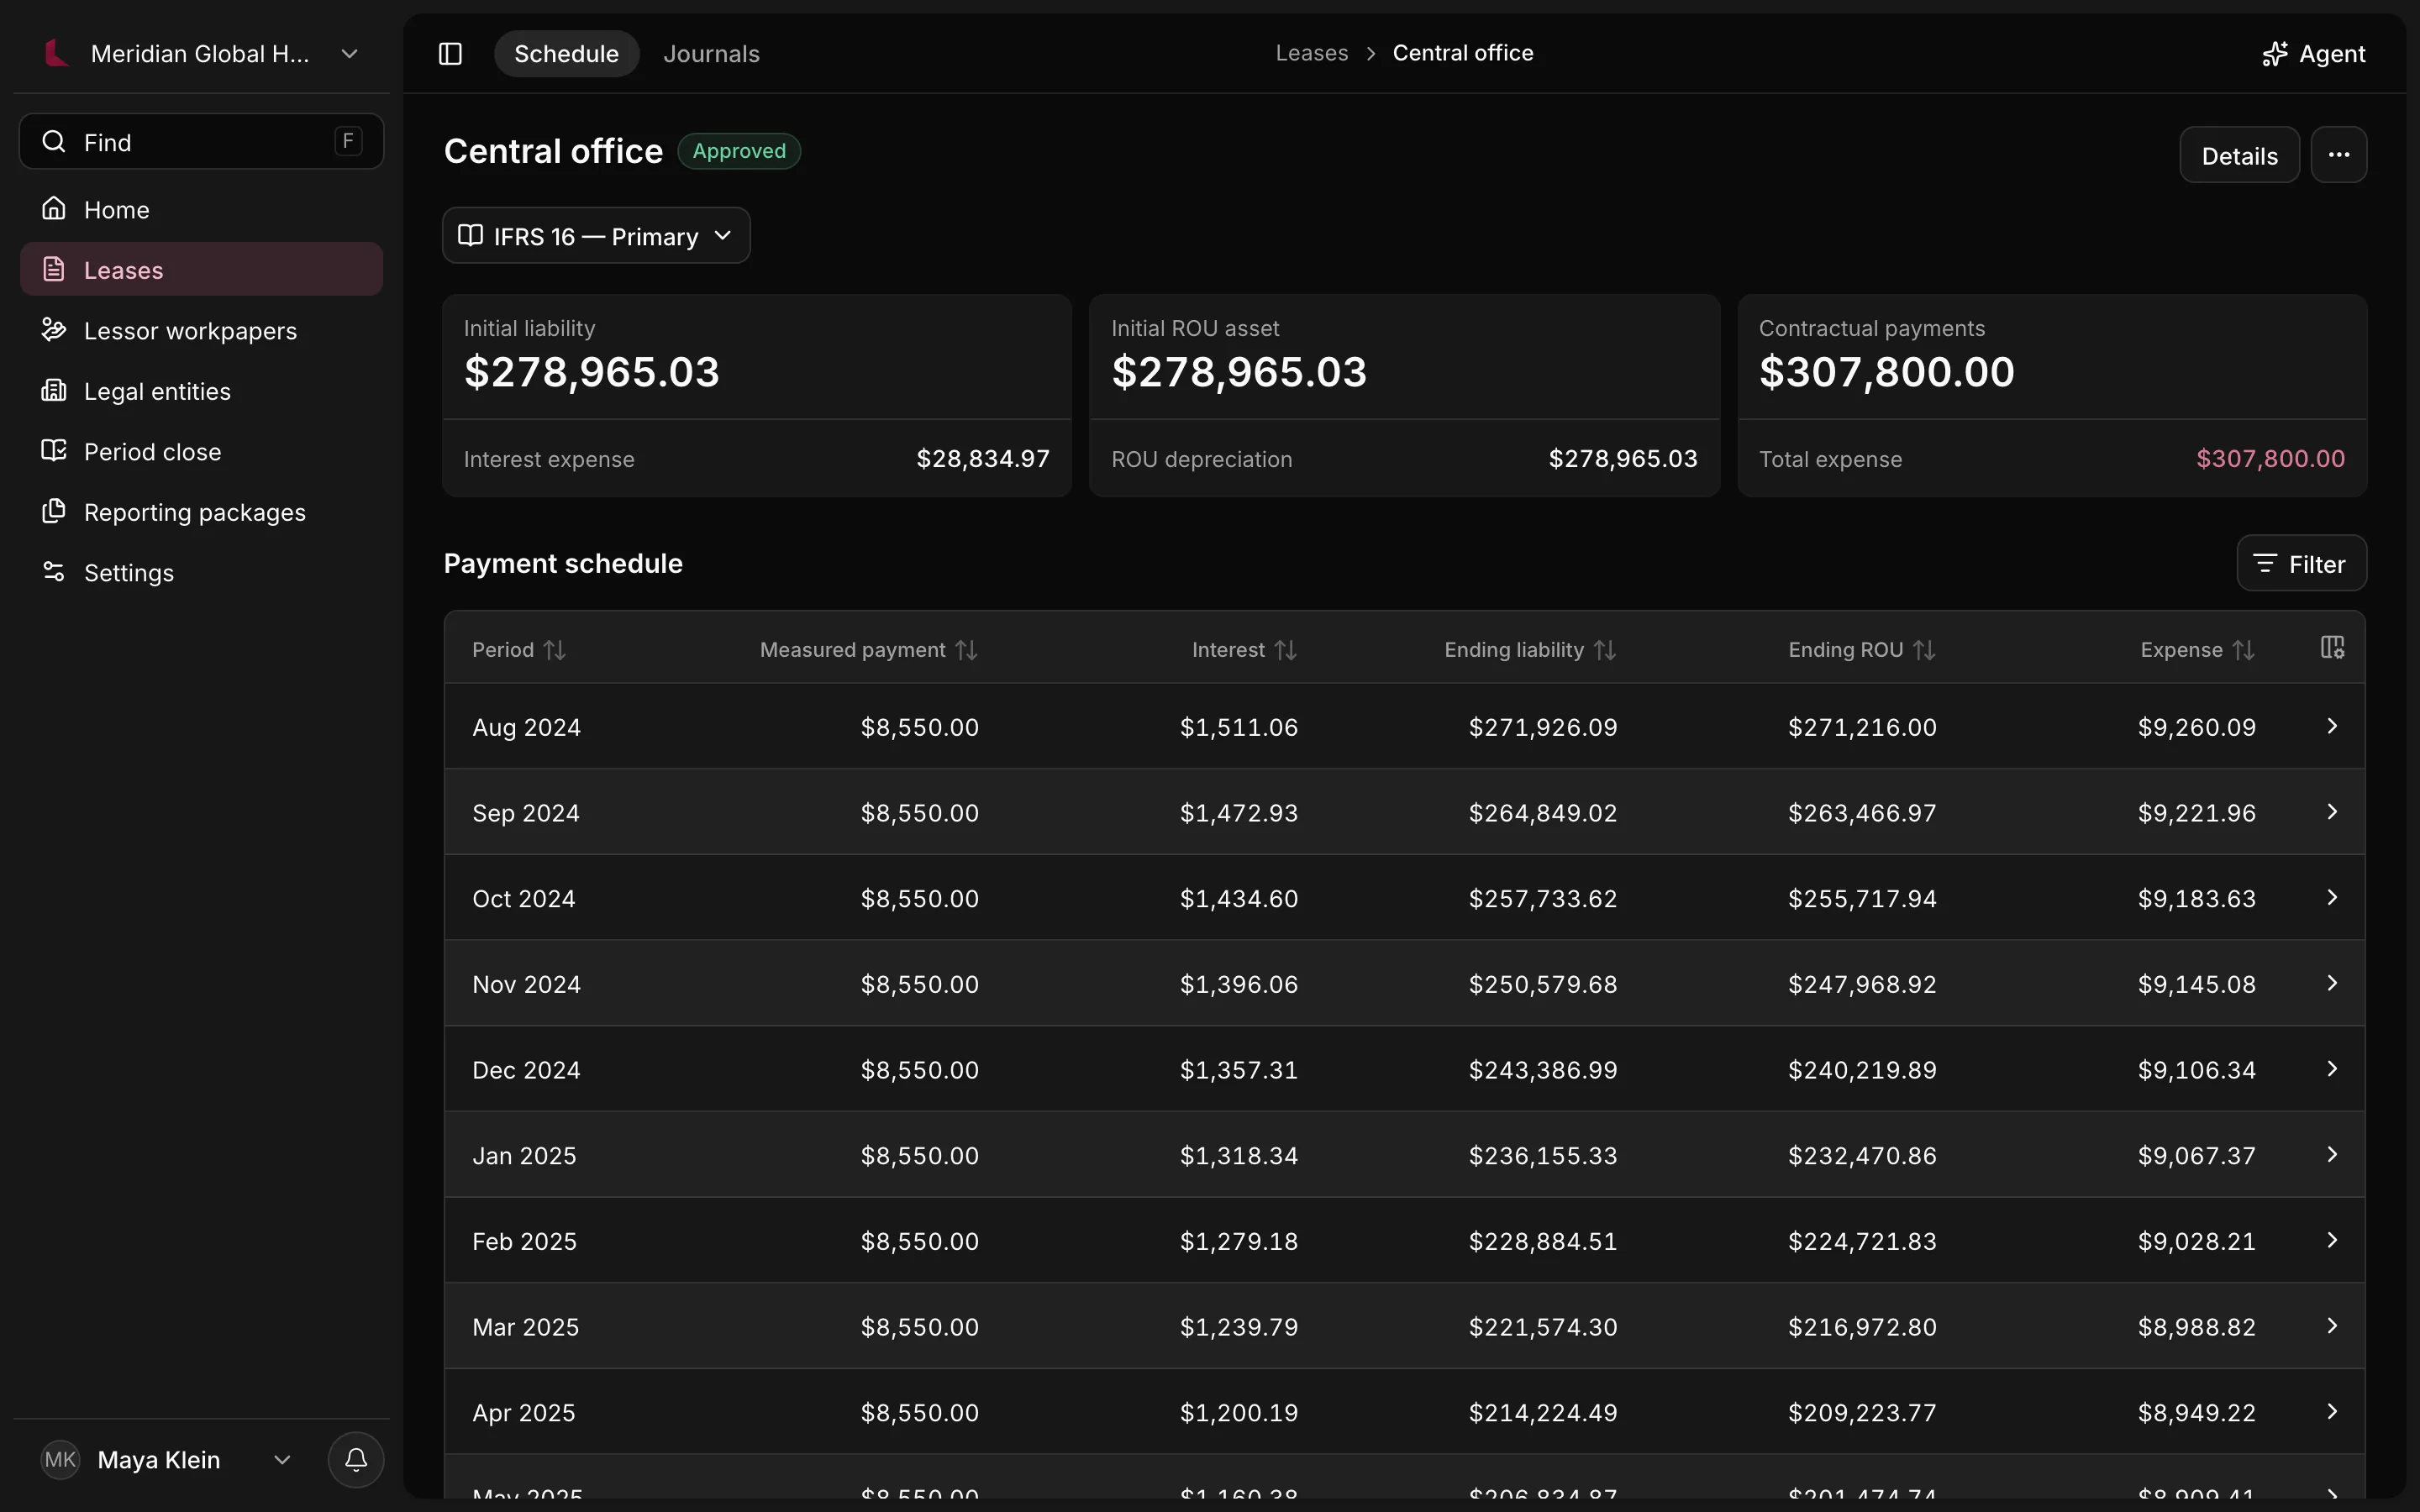
Sealed inputs. The lease is approved. Calculation v3 is derived from a hashed snapshot, 9cbb2f7e, never from editable rows.
Two books. Each reporting book carries its own standard, classification and policy. Switch books; the facts stay put.
Exact arithmetic. Interest of 1,511.06 is 278,965.03 at 6.50% for one month, in decimal arithmetic, to the cent.
01How it works
Leasecount follows a lease the way your auditor will, one approved step at a time.
Contract facts are entered once, agreed to the signed lease and sealed on approval.
Payment schedule
Central office · lease clause 4.1
Meridian Global · FY2024
RuleFixed 8,550.00 USD · monthly · in arrears · 36 periods
| Period | Due | Payment |
|---|---|---|
| Aug 2024 | 31 Aug 2024 | 8,550.00 |
| Sep 2024 | 30 Sep 2024 | 8,550.00 |
| Oct 2024 | 31 Oct 2024 | 8,550.00 |
| Nov 2024 | 30 Nov 2024 | 8,550.00 |
| Dec 2024 | 31 Dec 2024 | 8,550.00 |
| Jan 2025 | 31 Jan 2025 | 8,550.00 |
| Feb 2025 | 28 Feb 2025 | 8,550.00 |
| … 29 more periods to Jul 2027 | ||
| Total, 36 payments | 307,800.00 | |
Approval and input snapshot
Central office · version 1
Meridian Global · FY2024
Canonical snapshot hash
bbf8c256ee0d444cfd4f100754e64651
cfc722a39487b8f6fb1e03bc33ccc77d
Each reporting book keeps its own judgement, schedule and journals.
Year-one expense, two books
Central office · 36 × 8,550.00 at 6.50%
IFRS 16 and US GAAP
Year-one expense · same lease, same facts
$108,559
Cost model: depreciation plus front-loaded interest.
Lease classification
Central office · ASC 842-10-25-2
US GAAP — Parallel
Conclusion. No test met. IFRS 16 applies its single lessee model to the same facts.
OperatingJournal · August 2024
Central office · posting batch 1
IFRS 16 — Primary
| Account | Dr | Cr | |
|---|---|---|---|
| Lease liabilities | 7,038.94 | ||
| Interest expense | 1,511.06 | ||
| Cash and bank | 8,550.00 | ||
| ROU depreciation | 7,749.03 | ||
| Accumulated depreciation | 7,749.03 | ||
| Total | 16,299.03 | 16,299.03 |
Index resets, reassessed options and terminations are worked from the balances on the day they happen.
Remeasurement · CPI reset
Central office · effective 1 Aug 2025
Meridian Global · FY2025
| IFRS 16 — Primary | US GAAP — Parallel | Work | |
|---|---|---|---|
| CPI, July 2025 (base 100.0) | 103.1 | 103.1 | Published index |
| Monthly payment from Aug 2025 | 8,815.05 | 8,815.05 | |
| Liability before the reset | 191,935.34 | 191,935.34 | |
| Remeasurement at 6.50% | 5,950.00 | — | 24 × 265.05 |
| Liability after the reset | 197,885.34 | 191,935.34 | |
| Variable lease cost | — | 265.05 / mo |
IFRS journal. Dr Right-of-use asset 5,950.00 · Cr Lease liabilities 5,950.00
US GAAP. No remeasurement until another qualifying event.
Calculation v2 sha256 17927b51442833b9
SealedCalculations and journals go to designated approvers, and self-approval can be forbidden.
Change report · option reassessed
Central office · calculation v2 → v3
IFRS 16 — Primary
| v2 | v3 | |
|---|---|---|
| Lease term | 36 months | 48 months |
| ||
| End of measured term | 31 Jul 2027 | 31 Jul 2028 |
| Renewal option | Not reasonably certain | Reasonably certain |
| Schedule rows | 36 | 48 |
Self-approval is prohibited by this organization's control policy, so the preparer cannot approve v3.
ApprovedDR · 03 Feb 2026Disclosures reconcile to the cent and freeze into a package with a content hash.
Close readiness · August 2026
64 leases · Meridian Commerce
IFRS 16 — Primary
Reporting package
rollforward-2026-08.csv · sha256 4e1a90c7
Maturity analysis
Central office · undiscounted, USD
IFRS 16 — Primary
2024 Aug–Dec
2025 Full year
2026 Full year
2027 Jan–Jul
02Immutable history
Each recalculation is stamped with the hash of its inputs and stacked on the one before it. Nothing underneath is replaced, so any number can be explained as of any date.
v1
commencement
v2
CPI reset
v3
option reassessed
v4
rate revised
v5
partial termination
03Try the maths
Move the sliders. The liability unwinds with interest while the right-of-use asset depreciates in a straight line.
Illustrative, in your browser. Leasecount itself measures with decimal arithmetic, exact calendar dates and the approved snapshot, never floating point.
Hover the chart to inspect any period.
04Product
Real screens from a demo workspace with 64 leases across two entities and two reporting books.
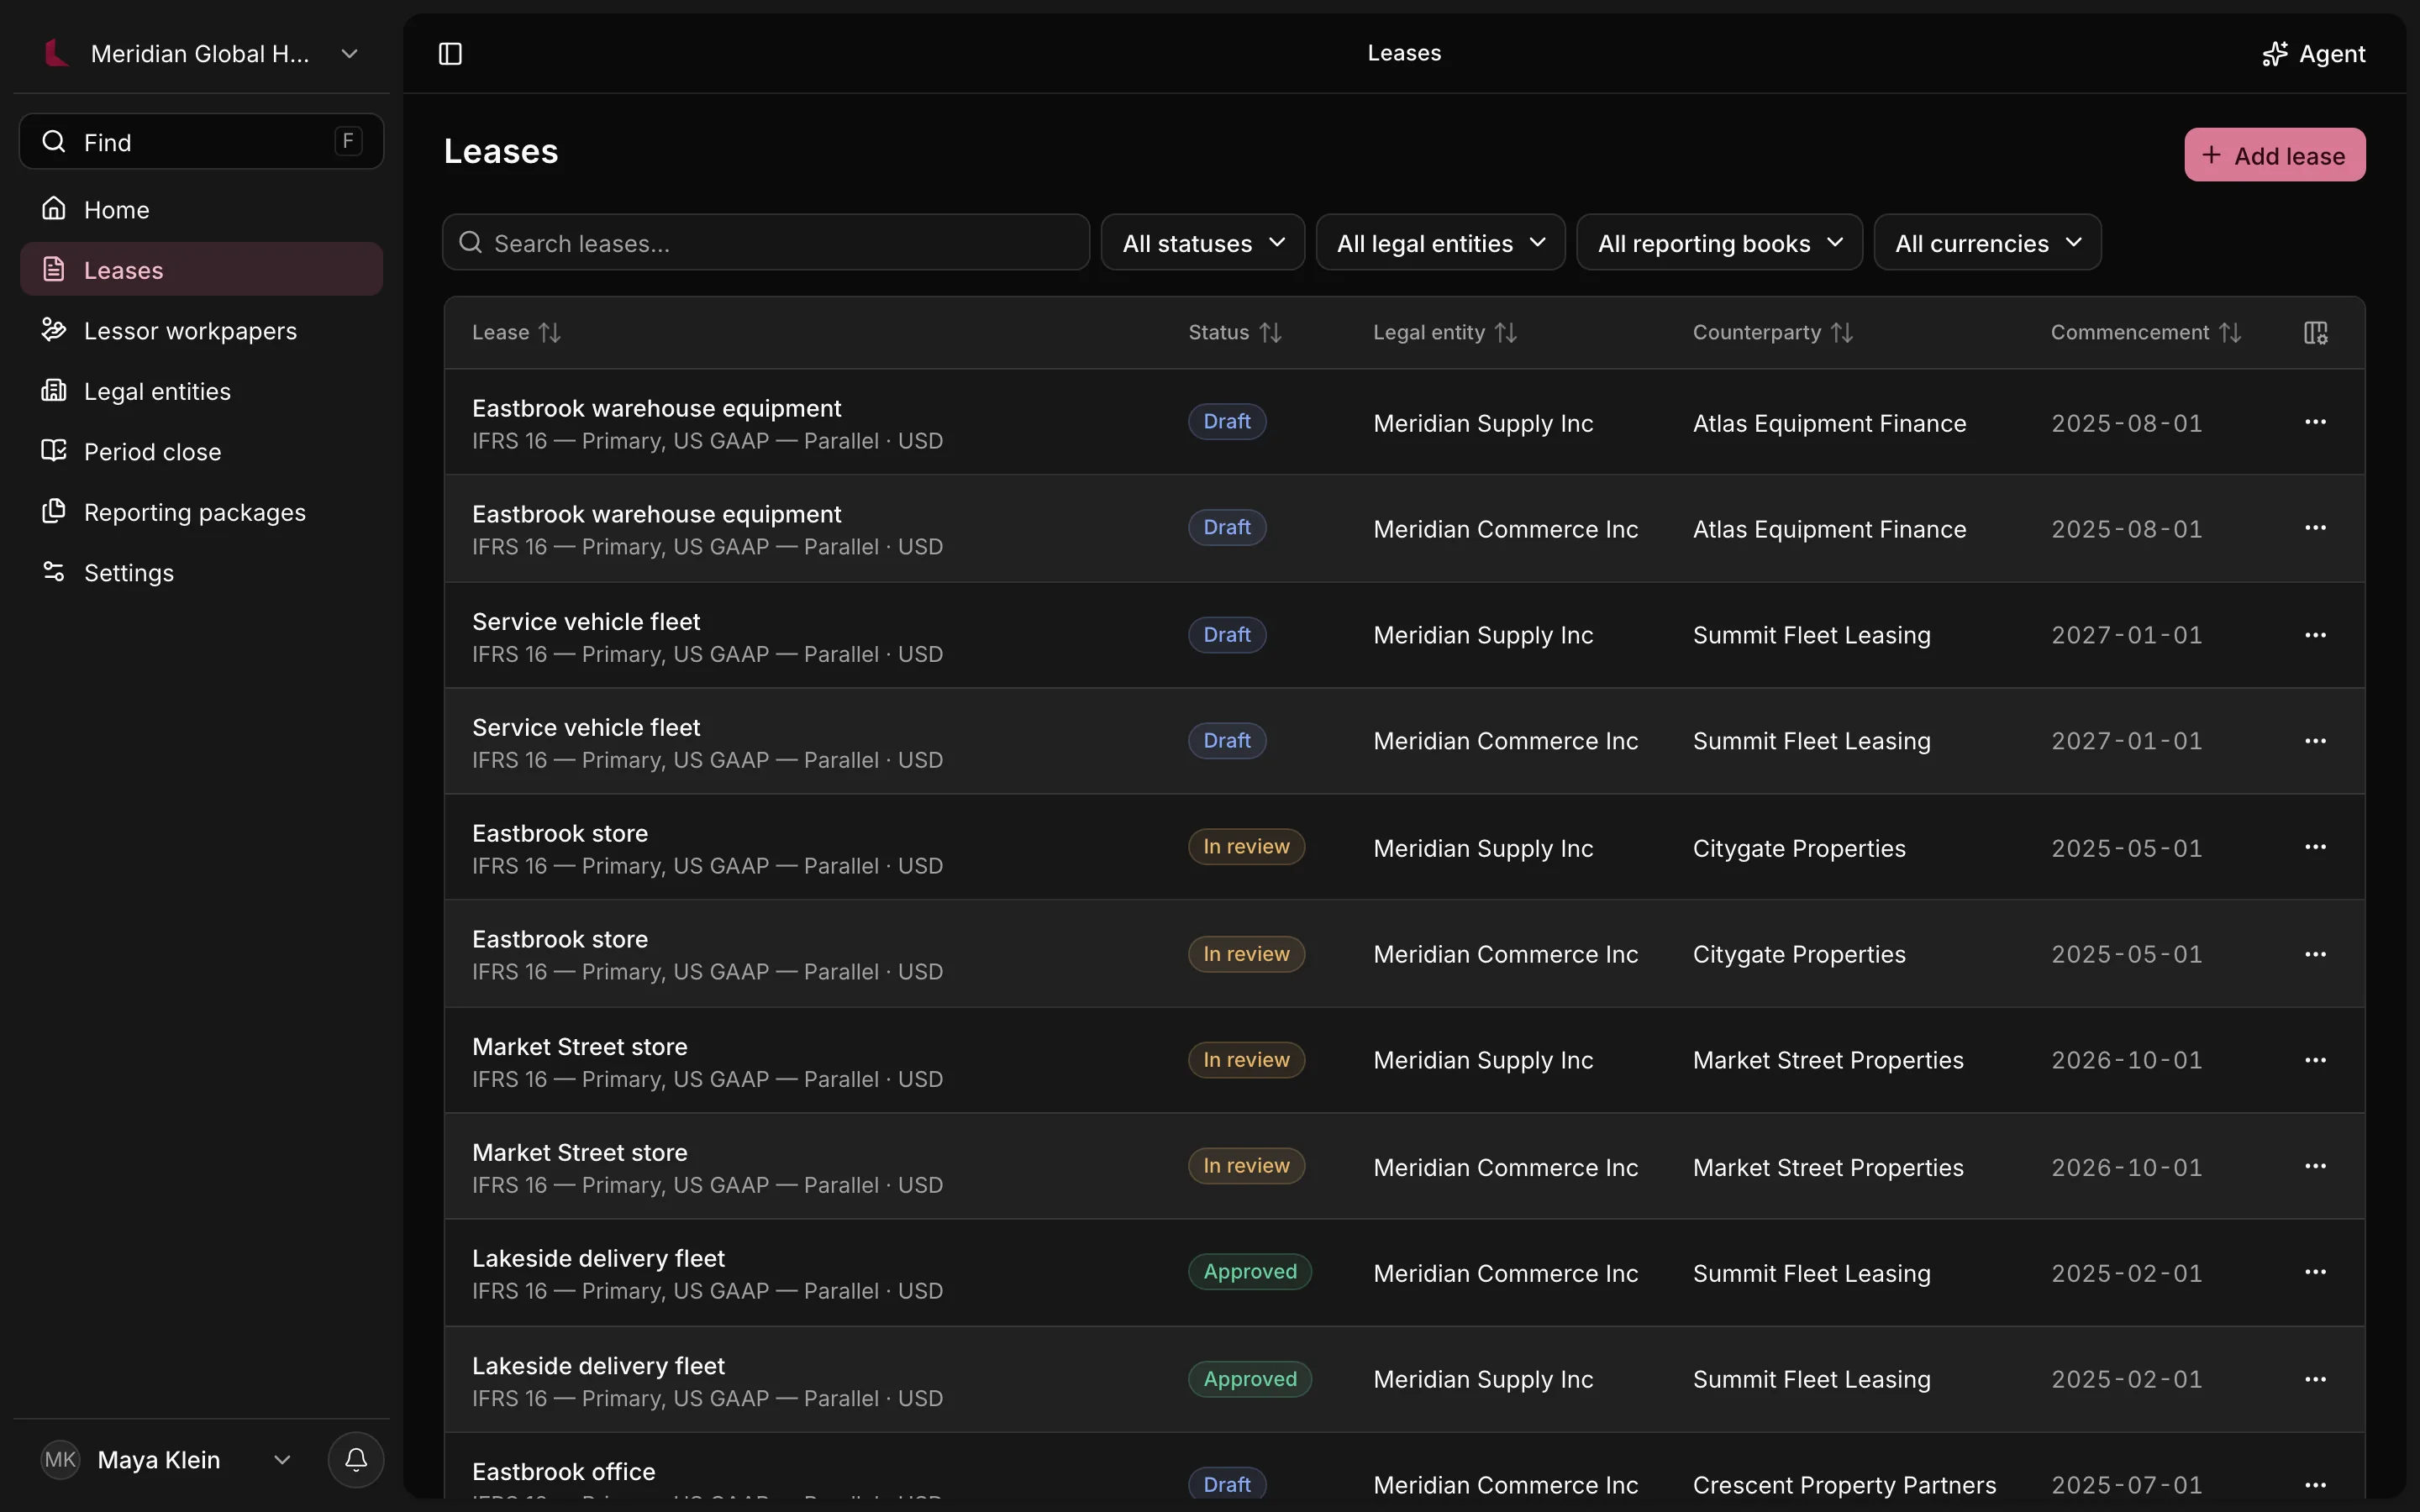
Every contract in one register. Filter by status, entity, book and currency, and the URL keeps your view.
05Security
An organization is a hard boundary, and every read, write and export is authorized on the server.
Hard tenant isolation. Every record carries its organization. Server-side authorization guards reads, writes, exports and jobs.
Roles and approvals. Owners, admins and members with designated approvers and optional self-approval prohibition.
Defense in depth. Database constraints keep journal and calculation provenance from crossing organization or lease scope.
Careful authentication. Verified sign-up, rate-limited one-time codes, secure resets and session revocation.
06Pricing
Every plan includes every accounting feature and unlimited users. Each organization is billed on its own.
For a single company bringing its first leases out of a spreadsheet.
$49
per month, per organization
For finance teams running a growing portfolio across a few companies.
$129
per month, per organization
For multi-entity groups with parallel books and a monthly close.
$299
per month, per organization
For larger portfolios, custom limits and procurement requirements.
Custom
Annual agreement
Seven-day trial on every plan. Prices in USD. Compare plans
Questions
Something else? Write to us and a person will answer.
Leasecount is built for lessee accounting under IFRS 16 and ASC 842 (finance and operating), with multiple reporting books per entity. It also covers lessor workpapers, subleases and sale-and-leaseback within an explicitly supported scope. Anything outside the supported boundary is rejected clearly rather than approximated.
No. Leasecount records your judgements, including classifications, elections, rates, rationale and evidence, and computes from them. Recommendations and validation rules are workflow aids, not an accounting opinion, and the product makes no certification claim.
Every calculation version is immutable and records its inputs, engine version, hashes and the approved snapshot it came from. A change creates a new version that supersedes the old one, and approved journals are corrected by reversal, not edits.
Yes. An organization can have several legal entities and reporting books. Contract facts are shared; each book keeps its own standard, judgements, schedules, journals and close.
Schedules, journals and reporting packages export as CSV. Each export is generated by a background worker, hashed and stored durably with the actor, scope and time, so you can prove what was downloaded.
Users are unlimited on every plan. Each organization has its own subscription and limits on active leases, legal entities and storage. Plans start with a seven-day trial, and a card is required to begin it.
Bring in a contract, assign your books and see the schedule your auditor will ask for.